
Calls to redistribute the fortunes of the super-rich may be politically attractive. But as Harry Margulies explains, governments risk destroying the value they hope to tax if they mistake productive capital for cash
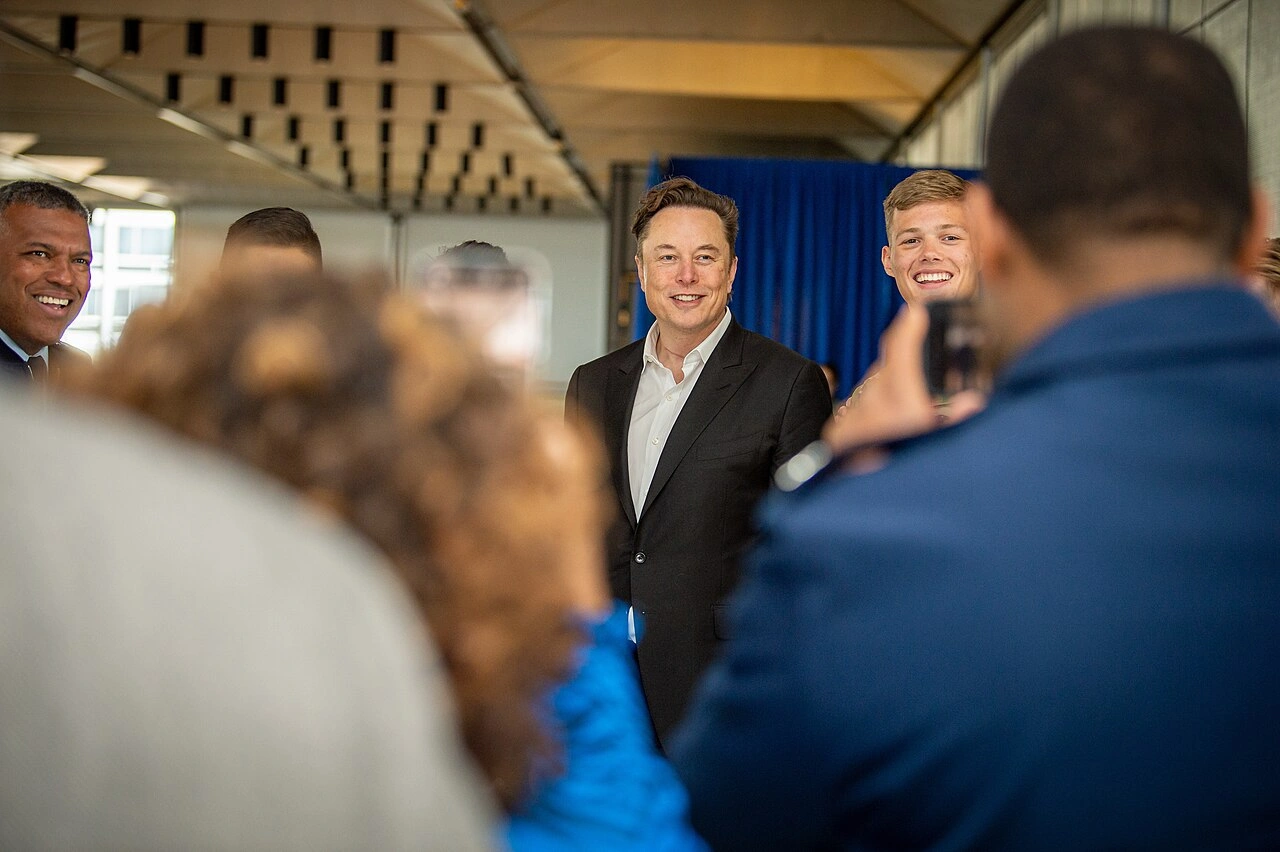
Last month, Elon Musk became the world’s first trillionaire following the flotation of SpaceX. The company’s record-breaking stock-market debut lifted estimates of Musk’s net worth to approximately US$1.1 trillion.
The milestone predictably renewed debate about whether any individual should be permitted to possess such enormous wealth, and how much of it governments should tax and redistribute.
But Musk does not have US$1 trillion sitting in a bank account, readily available for taxation. Most of his fortune consists of ownership stakes in businesses whose values reflect what investors believe those companies may produce in future.
The French economist Thomas Piketty has proposed a 90 per cent wealth tax on fortunes over €2 billion, effectively placing a very low ceiling on how much wealth an individual could retain.
But even if we adopt a generous hypothetical limit for trillionaires of US$200 billion, the practical problem remains. If Musk were notionally worth US$1 trillion, approximately US$800 billion would have to be taxed away.
Because that wealth is not held in cash, the government could not simply demand an electronic transfer. It would have to acquire a substantial proportion of Musk’s shares or force him to sell them.
Either option creates problems. If the government retained the shares, it would become an influential owner of some of the world’s most consequential enterprises. Investors would reasonably begin asking whether political priorities might affect corporate decisions.
If the shares were sold instead, markets would have to absorb an enormous increase in supply. Their price would almost certainly respond accordingly.
The value being taxed, then, cannot be separated from the mechanism used to extract it.
Much of Musk’s estimated wealth is also based on investor confidence in his ability to deliver future growth. Analysts have even referred to an ‘Elon premium’ – a valuation attached not only to the assets and revenues of his businesses, but to faith in Musk himself.
A policy that substantially diluted his control, displaced him or turned his companies into state-influenced enterprises could therefore change the assumptions on which their valuations were based.
This is not to say that the ultra-wealthy should be exempt from tax. Rather, it means that paper wealth cannot be treated as though it were a cash pile waiting to be divided.
Musk’s own position illustrates its instability. His net worth rose above US$1 trillion following the SpaceX flotation, subsequently fell below that threshold and then returned above it as the value of his holdings changed.
Nothing had been removed from or returned to a vault. The market had simply revised what it believed his assets were worth.
Musk’s fortune represents one extreme of a wider political tendency on both sides of the Atlantic to treat every increase in asset value as readily taxable income. The same assumption appears, in less dramatic form, in proposals to tax capital gains at income-tax rates.
With Sir Keir Starmer stepping down and Andy Burnham expected to succeed him, Britain is once again debating its economic direction. A more left-leaning Labour leadership may bring renewed calls to tax capital gains at the same levels as ordinary income.
The argument sounds compelling: those with the greatest ability to pay should contribute more, and apparently similar economic gains should be taxed similarly.
But capital gains are not the same as income, just as the paper wealth of Musk is not income. Income is generated by productive activity or an underlying asset. Your labour produces wages. Shares produce dividends. Government bonds produce interest. As long as the activity or asset continues to exist, it can continue producing taxable income for its owner.
A capital gain, by contrast, arises when ownership of an asset changes hands.
Consider a simple example. Suppose you discover a seed, plant it and grow an apple tree. The tree is your capital. Every year it produces 100 apples. Those apples are your income.
One day, someone offers to buy the tree for £1,000 because he believes that better cultivation would allow it to produce 200 apples a year. Once he owns it, he will pay tax on the greater income it generates.
Society benefits because a productive asset has moved to someone who believes he can use it more efficiently.
Now imagine that selling the tree triggers capital gains tax at the same rate as income tax. If the cost base is zero and half the proceeds disappear in tax, you are left with £500 rather than the £1,000 you had expected to reinvest. You may, therefore, decide not to sell.
The result is not necessarily greater fairness. The tree remains with the less productive owner, fewer apples are produced, less income is earned and, ultimately, less tax may be collected.
This illustrates why many countries distinguish between capital gains and ordinary income. The purpose is to avoid locking productive assets into the hands of people who are no longer best placed to use them. Economic growth depends on capital being able to flow towards those who can employ it most productively.
There is another reality of tax policy that Britain cannot ignore: it is not a closed economy. Capital is mobile, entrepreneurs are mobile, and investors are increasingly mobile. Countries are, therefore, competing for entrepreneurs, innovators, investors and the capital that creates future employment.
Many European countries, for example, openly use their tax systems to attract wealthy residents and investment. Italy offers qualifying arrivals a fixed annual charge on foreign income, for example, while Spain provides favourable treatment to many people who move there for work.
The United States has addressed this by taxing its citizens on their worldwide income even when they move abroad, substantially reducing the tax advantage of relocation.
Britain, however, has always competed directly with other jurisdictions to attract and retain internationally mobile wealth. That is why the UK’s decision to move in the opposite direction by abolishing its long-standing non-dom regime seems somewhat counterproductive.
The replacement system, which came into effect last year, gives qualifying new residents relief on foreign income and gains during only their first four years in the country. After that, they are generally taxed on worldwide income and gains.
That may be considered fairer, but fairness is not the only relevant test. Policymakers must also consider how internationally mobile people will respond. A future Burnham government should therefore remember that if one country makes itself less attractive, others are prepared to welcome the people and capital that leave.
The tax structure in Sweden offers another useful lesson. It once combined high income taxes with taxes on wealth, inheritance and gifts. It later abolished all three of the latter taxes while retaining an extensive welfare state.
A recent empirical study into the abolition of Sweden’s inheritance and gift taxes found that private companies with potential family successors subsequently grew faster, invested more and paid more in corporation tax than comparable firms without likely heirs.
The state thus surrendered one form of tax revenue but appears to have encouraged economic activity that generated other, recurring revenues.
The bottom line is that while governments should tax income, combat avoidance and ensure that everyone makes the required contribution, they must also recognise that taxation changes behaviour.
Even billionaires who publicly support higher taxation usually employ accountants and lawyers to ensure that they pay no more than the law requires. Some then give away large fortunes, but on terms they choose and through causes or foundations they control.
The political attraction of taxing wealth lies partly in the assumption that the burden will always fall on somebody richer. Most people can identify a class above their own from which they believe more could safely be taken.
But if higher taxes discourage productive investment, prevent assets from moving to more effective owners, depress the value of businesses or persuade entrepreneurs and investors to relocate, the pursuit of fairness can become self-defeating.
The same principle applies whether the target is the capital gain on a £1,000 apple tree or hundreds of billions of dollars in SpaceX shares.
Governments cannot redistribute wealth that has not first been created. The true test of tax policy is therefore not whether it appears equitable on paper but whether, over time, it produces a richer society capable of funding the public services and redistribution that voters expect.

Harry Margulies is a journalist, author, commentator, and public intellectual whose work interrogates religion, politics, and morality with sharp wit and fearless clarity. A second-generation Holocaust survivor, he was born in Austria and spent time in an Austrian refugee camp before moving to Sweden. Educated by Orthodox rabbis throughout his childhood, he ultimately abandoned faith in his teens—a journey that has shaped his lifelong commitment to secularism, critical thinking, and freedom of expression. His latest book, Is God Real? Hell Knows, has been described by ABBA’s Björn Ulvaeus as “funny, sharp, and unafraid.”
READ MORE: ‘Could Canada’s GlobalEye deal become the first test of a new Atlantic partnership?‘. Canada’s proposed multi-billion-dollar GlobalEye deal marks an intention to reduce reliance on the United States and deepen defence cooperation with Europe. Harry Margulies asks whether America’s neighbour is ready to pay the price of turning that ambition into lasting strategic policy.
Do you have news to share or expertise to contribute? The European welcomes insights from business leaders and sector specialists. Get in touch with our editorial team to find out more.
Main Image: Justin Pacheco / U.S. Air Force