Oil draws back after reaching highest since March

John E. Kaye
- Published
- News, Sustainability
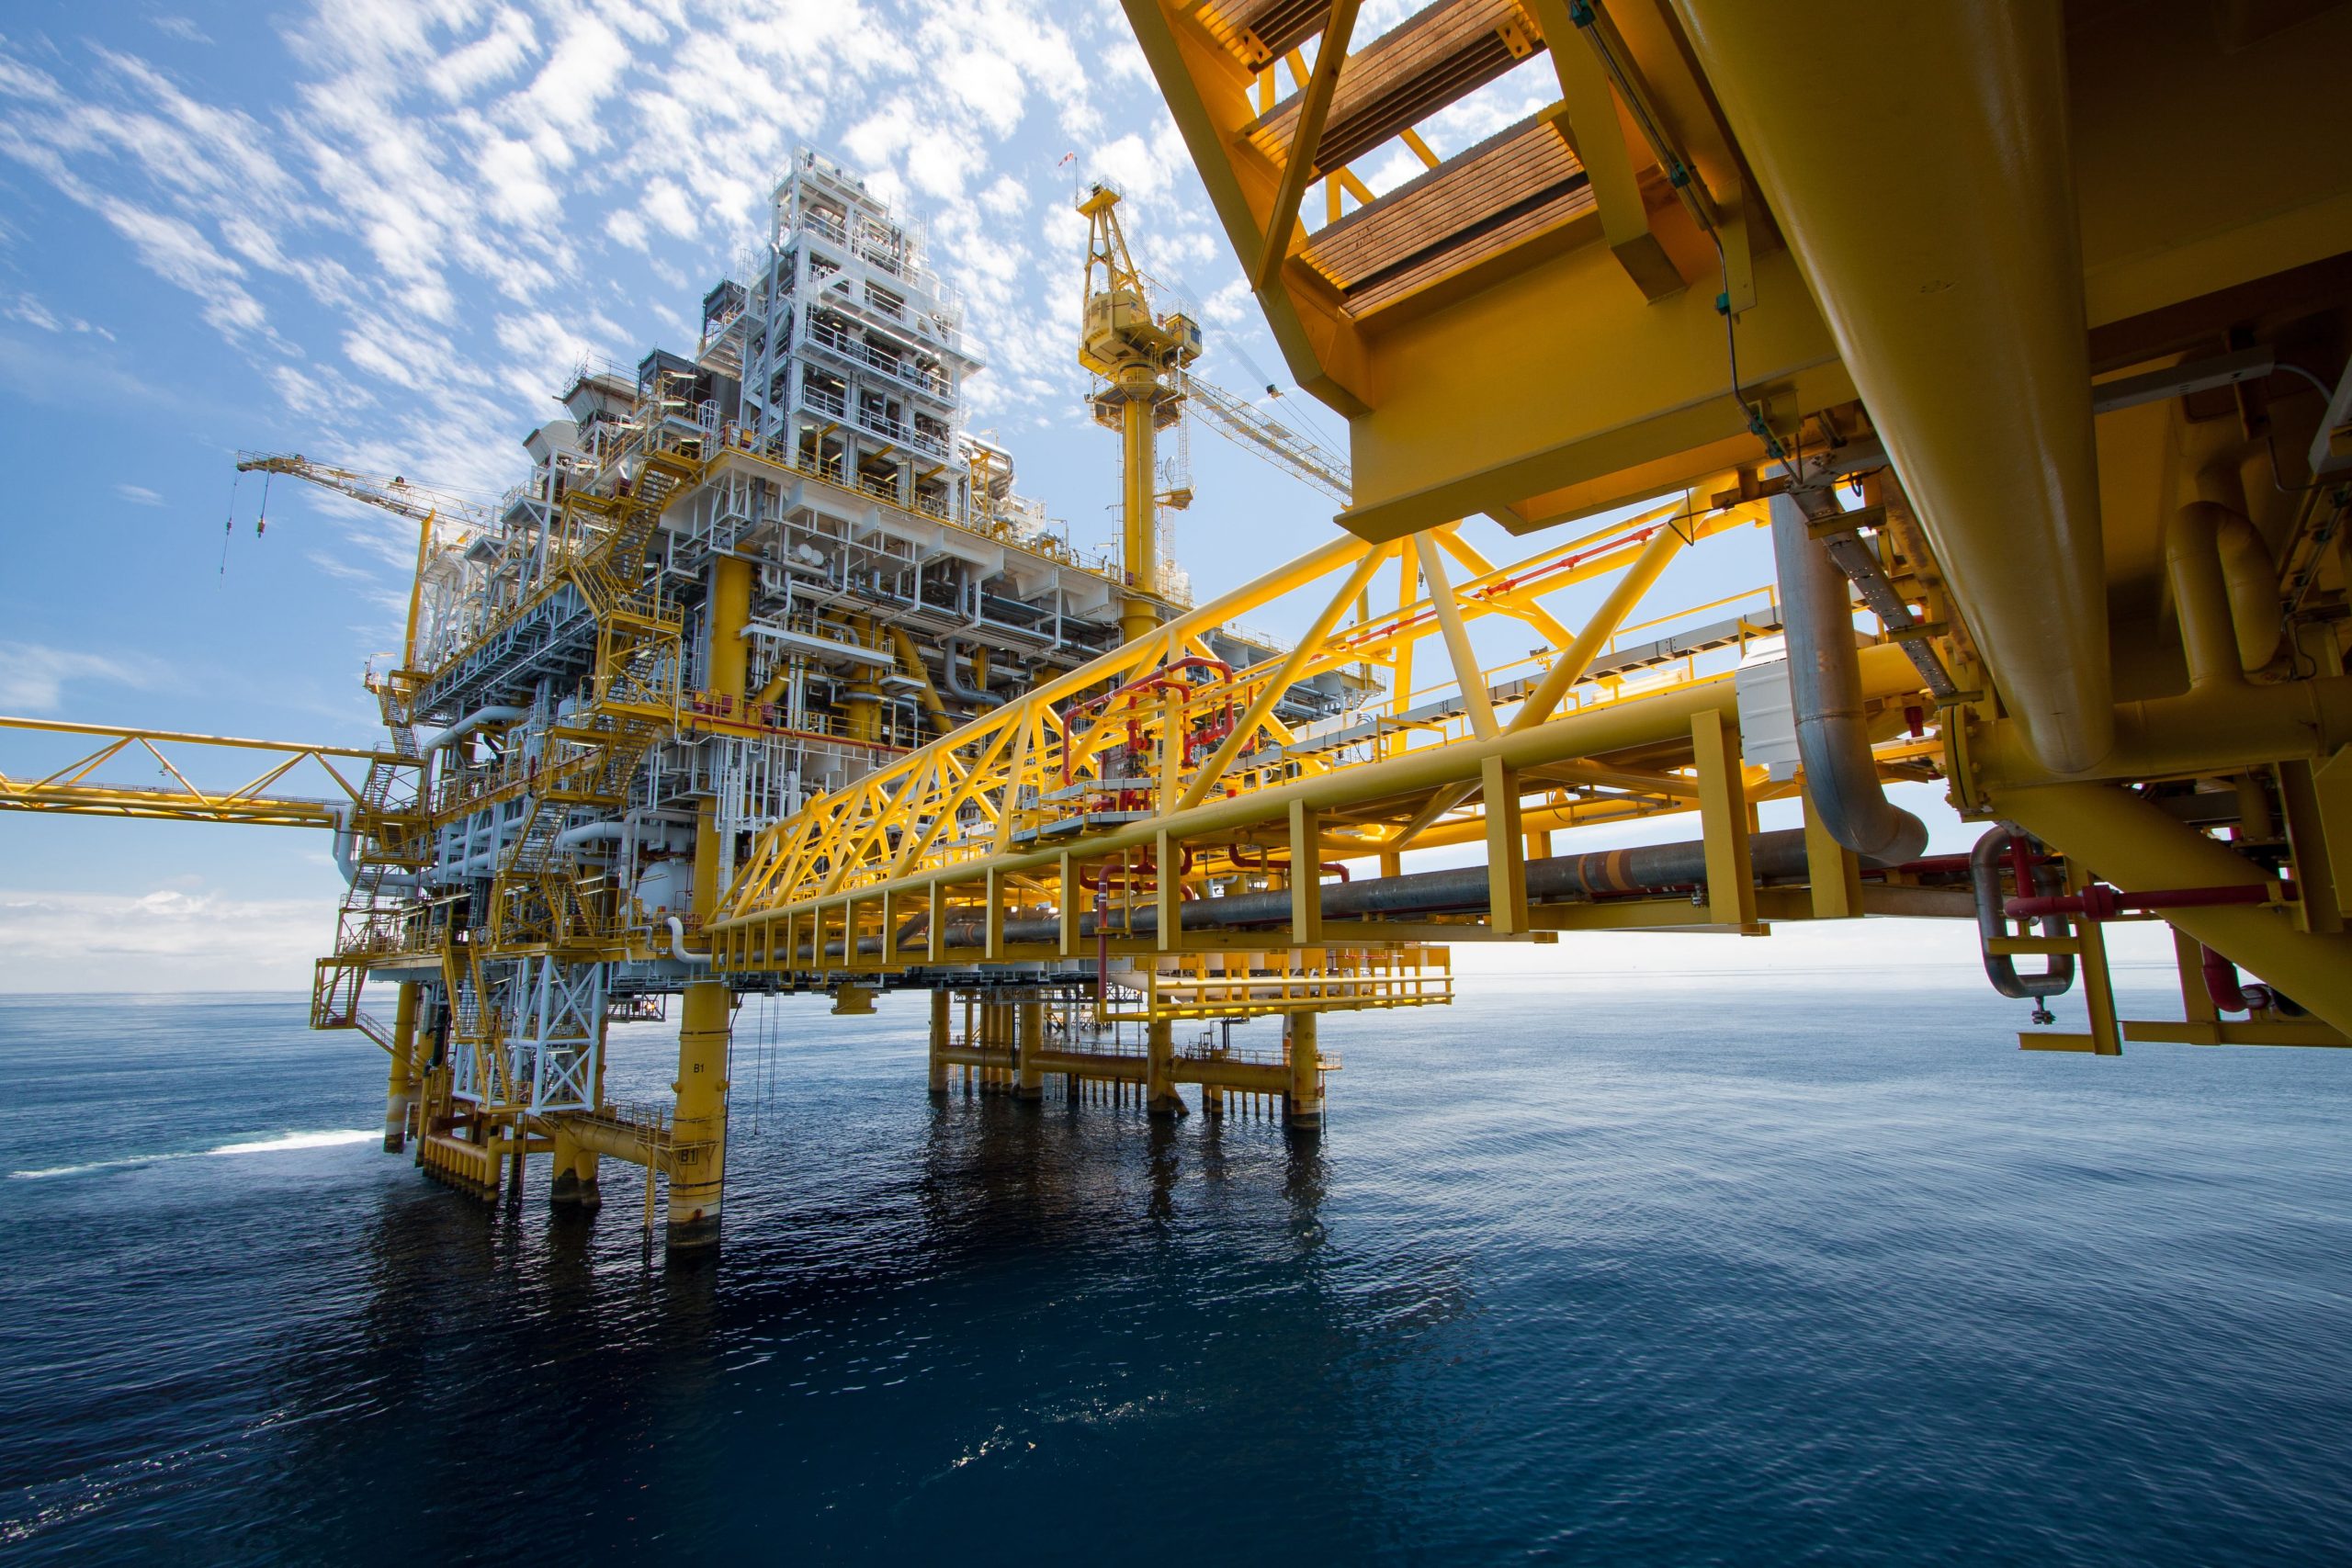
On Tuesday, Oil predictions slide as the market braced for reports expected to show swelling U.S. crude inventories, which pulled prices back off the highest levels since before the coronavirus pandemic slammed fuel demand.
Prices rose early, after U.S. President Donald Trump wrote a tweet late Monday regarding the trade agreement with China commenting the situation is “fully intact”. Markets had been unsettled by surprise comments from White House trade adviser Peter Navarro that the hard-won deal with China was “over”.
However, crude benchmarks declined in afternoon trade on expectations U.S. inventories will hit a record high for a third week in a row, undermining and impeding recent bullishness among investors.
Brent futures fell 45 cents, or 1.0%, to settle at $42.63 a barrel, while U.S. West Texas Intermediate (WTI) crude fell 36 cents, or 0.9%, to $40.37.
Oil extended losses in post-settlement trade after U.S. crude inventories rose by a much bigger than expected 1.7 million barrels last week, according to the American Petroleum Institute, an industry group. That compares with analysts’ expectations for a 300,000-barrel build. U.S. government data will be released on Wednesday.
Earlier, both contracts traded at their highest since prices collapsed on March 6 after the Organization of the Petroleum Exporting Countries (OPEC) and allied producers, including Russia, failed to agree on production cuts. Prices tumbled even further when the pandemic slashed fuel demand.
“It appears we ran into some technical resistance after closing the March 6 gap … and then we saw some profit taking,” said John Kilduff, partner at Again Capital LLC in New York.
U.S. crude stocks rose to 539.3 million barrels in the week to June 12, an all-time high, and are expected to have increased by 300,000 barrels in the week to June 19, according to a Reuters poll.
Additionally, weighing on crude prices, analysts said the market was unimpressed with purchasing managers reports in the United States, which showed the country’s rebound from coronavirus-depressed levels was not as sharp as in Europe.
Reported by Scott DiSavino
Sourced Reuters
For more Energy and Daily news follow The European Magazine
TOP STORIES
-
 Russia takes control of more European corporate assets amid Ukraine tensions
-
EU leaders resist calls to delay carbon rules as energy costs soar
-
‘A big step forward’ – PM Andy Burnham hails plans for Great British Railways HQ in Derby
-
UK economy grows just 0.1 per cent as construction falls and services stall
-
Germany risks losing €155bn a year under tighter AI data rules, new study warns
-
Pope Leo XIV diagnosed with lung cancer after surgery in Rome
-
France faces freezer meltdown as hackers strike supermarket chains
-
Bumble shares soar 50% amid $1bn takeover talks
-
China slump drives Volkswagen to sharpest quarterly fall in more than four years
-
Hollywood mega-powerhouse created as Paramount completes Warner Bros Discovery takeover
-
Gamers face gridlock as latest Grand Theft Auto download 'nears two days'
-
Samsung profits soar ninefold to record £61bn amid AI chip boom
-
New Springer books put the UN’s struggling sustainability goals to the real-world test
-
Europe’s solar boom set for two-year slowdown after record growth
-
Let it pea. Musicians turn vegetables into instruments at Beatles' Abbey Road studios
-
Golden naked Trump statue unveiled at European Parliament
-
Jaguar puts controversial rebrand on the road with £130K 1,030PS Type 01
-
Deepfakes and identity fraud drive new wave of post-hire background checks
-
Spain crowned Europe’s top retirement destination
-
More than half of UK professionals report workplace burnout
-
More than 1.2m English drivers may have eyesight too poor for the road, study finds
-
David Reuben, Britain’s second richest person, leaves London for Monaco
-
UK prisoner release plan faces a major lag as tougher rules risk sending inmates back to jail
-
Brits trust AI with their health but not their money
-
Britain still hungry for Italian food as exports hit €4.56bn despite Brexit