Why financial literacy looks different when you live between two countries

BOSS Money
Corporate Contributor
- Published
- Banking & Finance
Living between two countries can make everyday financial decisions more complicated, particularly when dealing with different currencies, exchange rates and family commitments abroad. Here, BOSS Money explores how greater financial awareness can help people manage their money more effectively across borders
Across the world, financial literacy and advice usually look the same: save money, have a monthly budget, and invest. However, what this advice means in practice often varies as one moves from one country to another.
Hence, financial literacy for immigrants tends to be more complex, as migrants attempt to manage dual-country budgeting and tax obligations amid exchange rate fluctuations.
Where Standard Advice Falls Short
Standard advice typically accounts for a single-country household, where budgeting, savings, and credit guidance are built around the prevailing economy.
What it often fails to account for is that most migrants have dual obligations that translate into supporting themselves in the host country, as well as supporting family abroad with remittances. According to IFAD’s Sending Money Home 2026 report, there are about 220 million migrants and diaspora members supporting 1.1 billion people (13.3 per cent of the global population).
Two Financial Systems at Once
Moving abroad sometimes comes with abandoning an impressive credit history back home, which, if transferred to the host country, could have made integration easier.
For many migrants, building credit as a newcomer is an enormous burden to carry while adjusting to different banking norms, credit scoring models, tax rules, and compliance in two different countries.
Consequently, savings, budgeting, and investment habits that apply in one country may fail in the other.
Currency and Cross-Border Costs
Volatile exchange rates can reduce the real value of a migrant worker’s earnings when they send money abroad. This is exacerbated by high transfer fees attached to international money transfers via traditional remittance services.
With the U.S-Brazil remittance corridor, for instance, users can lose up to $25.67 to poor exchange rates and high fees when sending US$200 via some providers.
But with some modern fintech solutions, users can get better exchange rates and as little as a US$0 fee on their first few transfers when transferring funds to Brazilian bank accounts.
Skills that Matter Most
Cross-border financial literacy starts with acknowledging that there are diverging factors in the mix, and adopting tools and strategies that enable adoption:
● Credit-building: Use reputable services that enable seamless credit-building and utilize cross-border credit transfer services if available to build credit history abroad.
● Tax obligations: Make it a duty to consult a tax expert to understand tax obligations in both countries and possibly avoid double taxation.
● Cost savings: Save on costs by researching and using reputable and cheaper fintech remittance services for single and recurring transfers.
Additionally, consider separating household and family-support budgets, being extra cautious to spot fraud aimed at immigrants, and seeking reliable financial guidance.
Where to Find Reliable Guidance
Migrants can avoid being overwhelmed by the idea of managing finances across borders by seeking guidance from:
● Official resources: Government-run websites for tax, credit, debt, and investments.
● Nonprofit financial counselors: Organizations that promote financial inclusion by providing free financial education, debt counseling, and budget management for immigrants.
Lastly, engage with immigrant-focused communities that serve people with similar backgrounds to access practical guidance from real experience.
Further Information
Produced with support from BOSS Money. To find out more about its international money transfer services, exchange rates and payment options, visit www.bossmoney.com
READ MORE: UK economy grows faster than first thought as household incomes bounce back. Revised official figures show stronger economic growth, rising household incomes and a surge in exports, with Britain outperforming Germany, France, Italy and the US during the second quarter of 2026.
Do you have news to share or expertise to contribute? The European welcomes insights from business leaders and sector specialists. Get in touch with our editorial team to find out more.
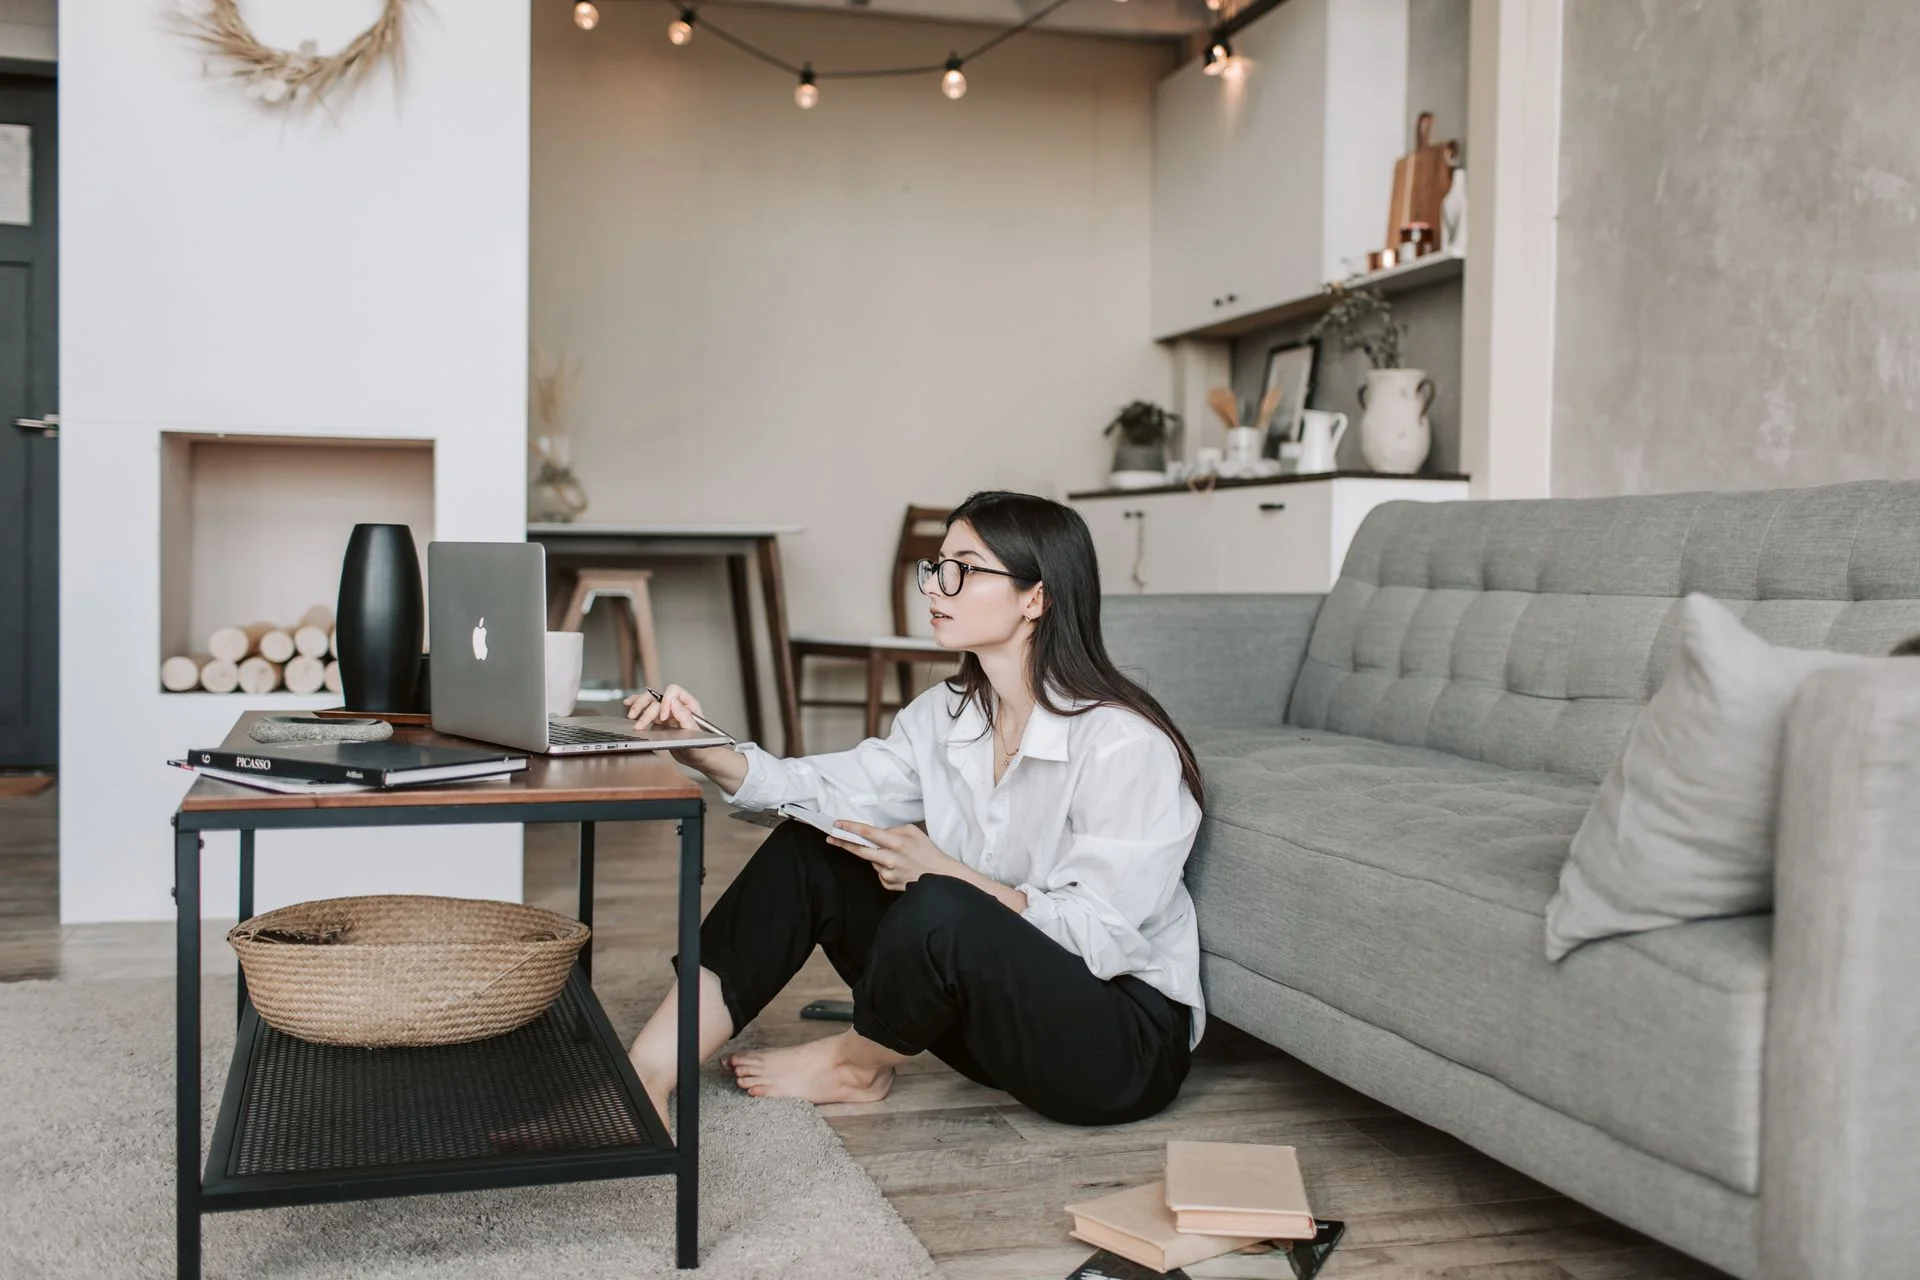
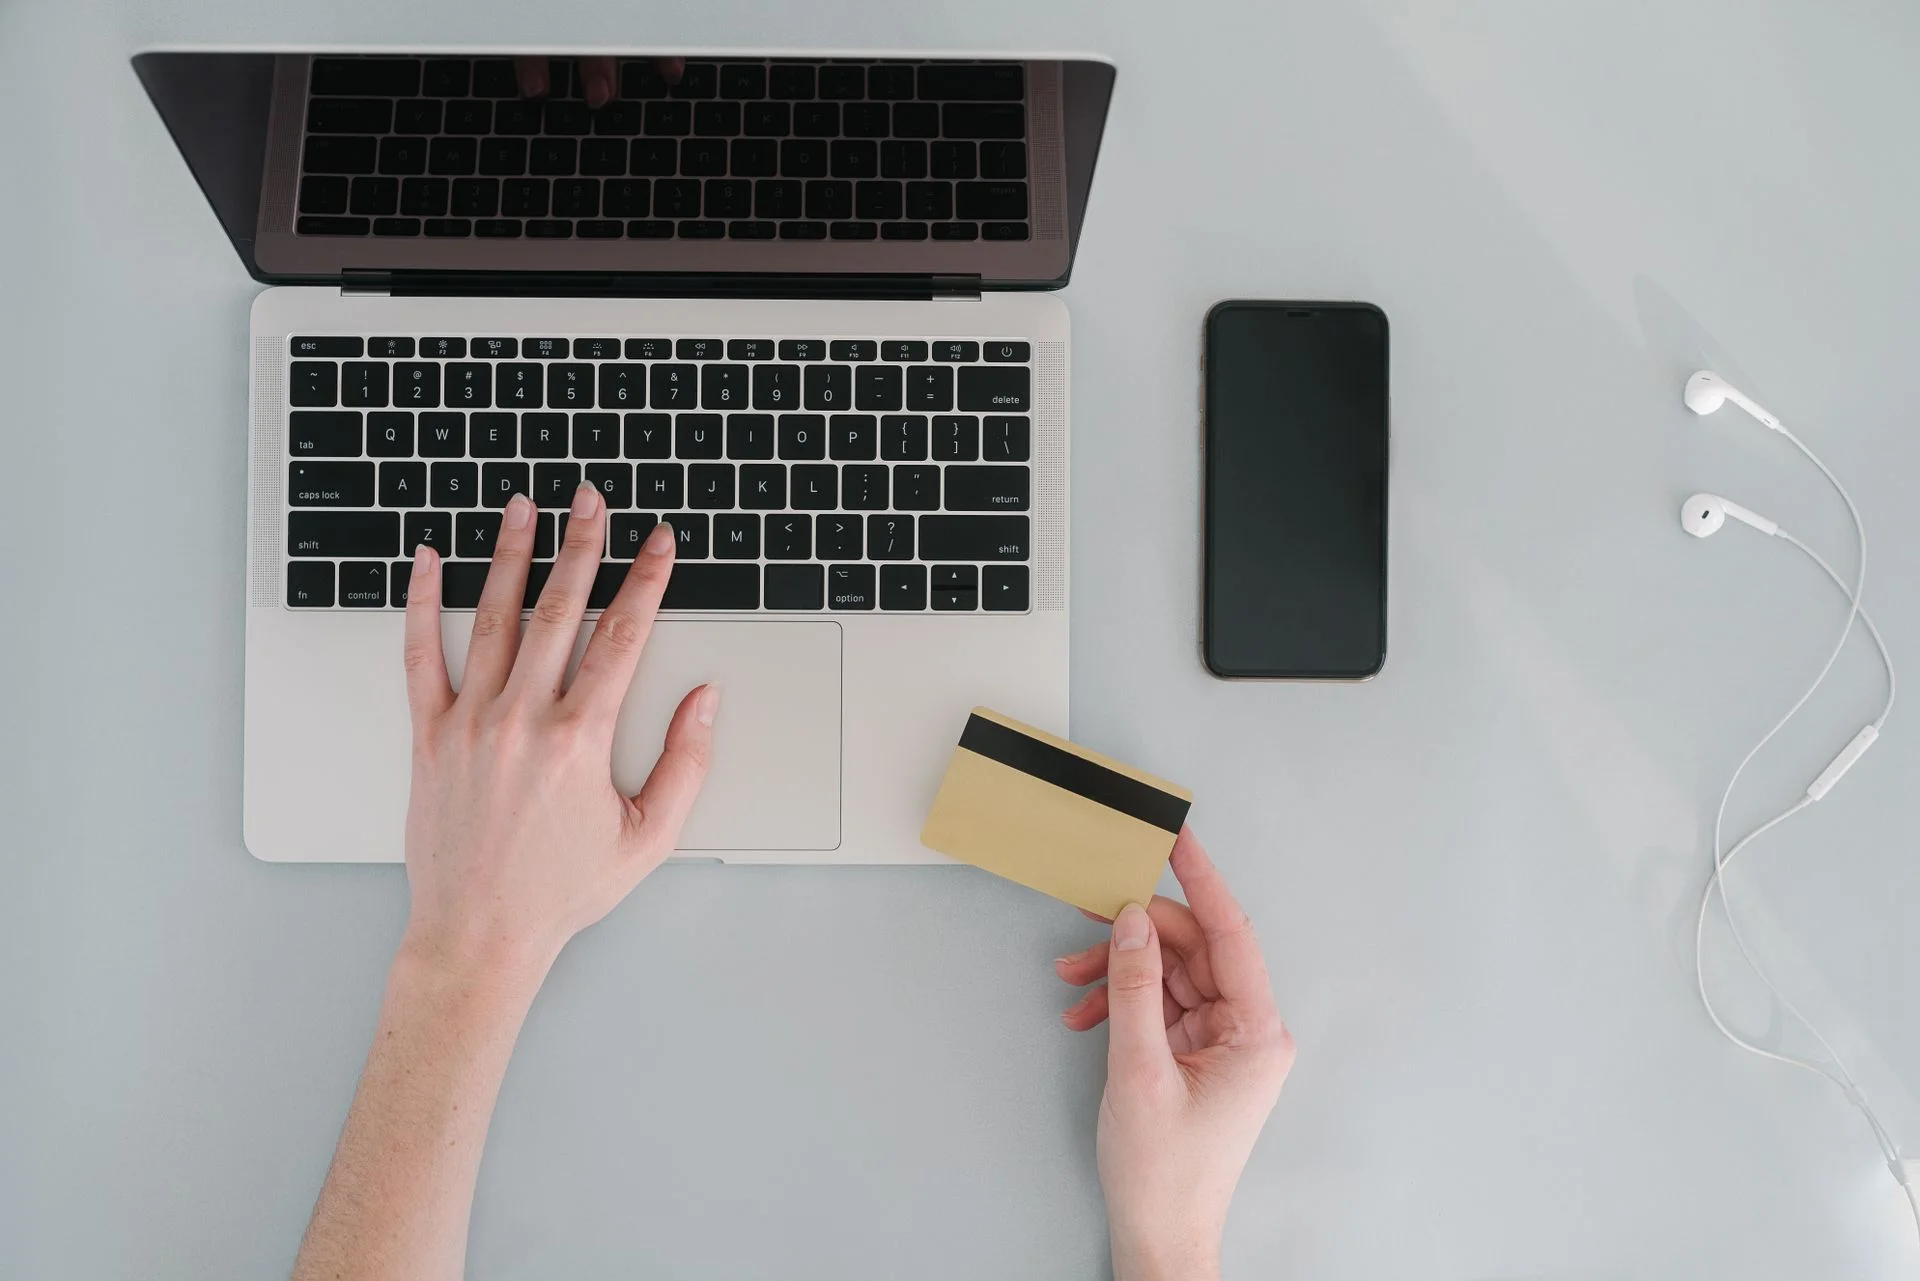
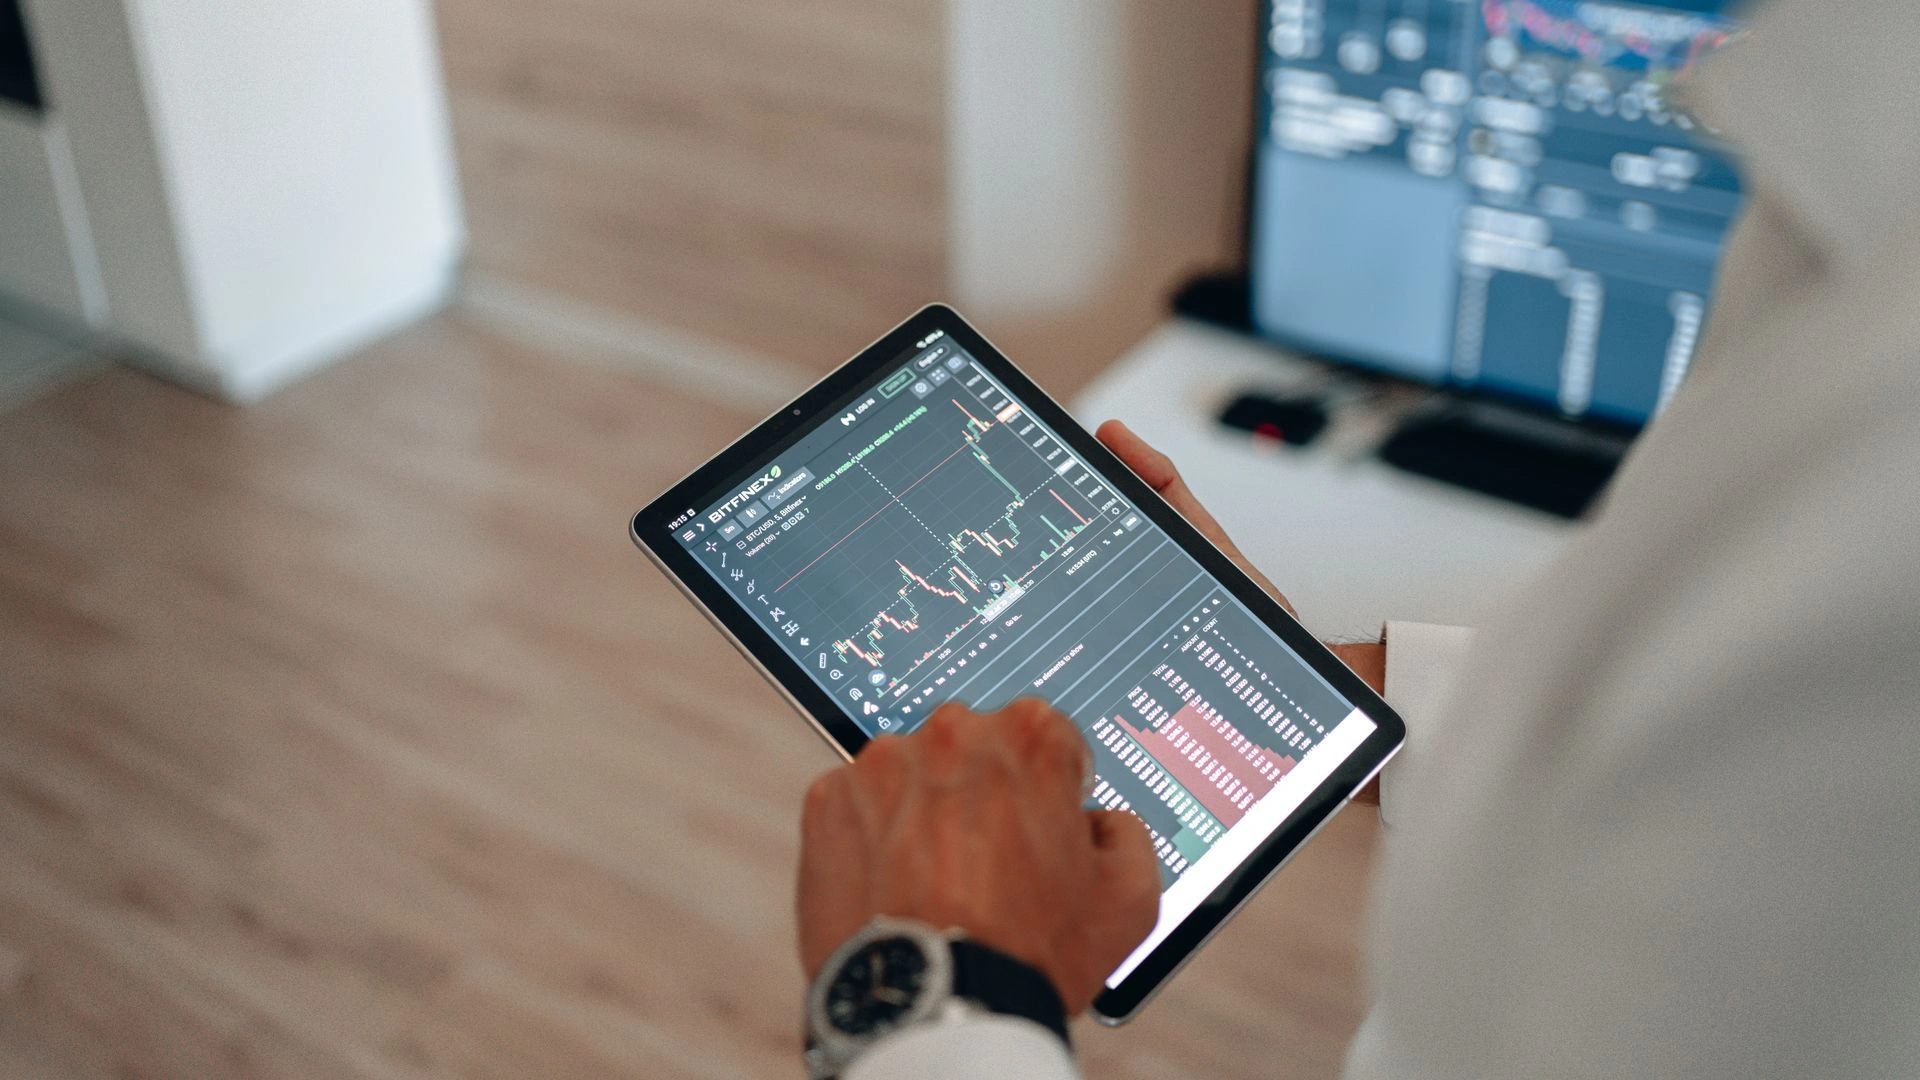
Main image: Managing money across borders requires careful financial planning, from budgeting for everyday expenses to supporting family overseas and navigating international payments. Credit: Vlada Karpovich/Pexels.
TOP STORIES
-
 Why financial literacy looks different when you live between two countries
-
TalkTalk sells majority stake in Telecom Acquisitions as founder Nigel Barnett regains control
-
Company closures soar ahead of tax rises as new Budget looms
-
Credit beyond scoring: where to find fintech’s next big opportunity
-
UK economy grows faster than first thought as household incomes bounce back
-
British Chambers unite against 'Made in Europe' rules amid fears for UK industry
-
Kuwait deepens capital market reforms as Boursa Kuwait scoops triple honours
-
Michael Dell becomes world's fourth-richest person as Forbes reveals the ten wealthiest billionaires
-
MPs tell Government to reject Thames Water creditors as utility nears insolvency
-
The municipal pension fund setting a new standard in South Africa
-
BP appoints Ian Tyler chairman after Albert Manifold ousting
-
They came to Malta as nomads. Then stayed on as founders
-
Fuel management software is becoming a working-capital tool for smaller fleet businesses
-
Tokenisation, trust and the future of European property law
-
LEGO sales soar 22% amid World Cup, F1 and Star Wars push
-
Why entrepreneurs choose the wrong countries
-
Finance and Investment in Focus
-
Aventus Group wins three European Business Awards after loan growth tops 30 per cent
-
European investors can now trade thousands of US stocks through Kraken
-
Ex-Lenovo executive Sabine Hammer to lead Infinigate’s DACH business
-
NVIDIA teams up with Wall Street giants in $500bn push to fund AI boom
-
BAC and the future of regional corporate banking in Central America
-
How AI trading bots are reshaping retail currency trading in Europe
-
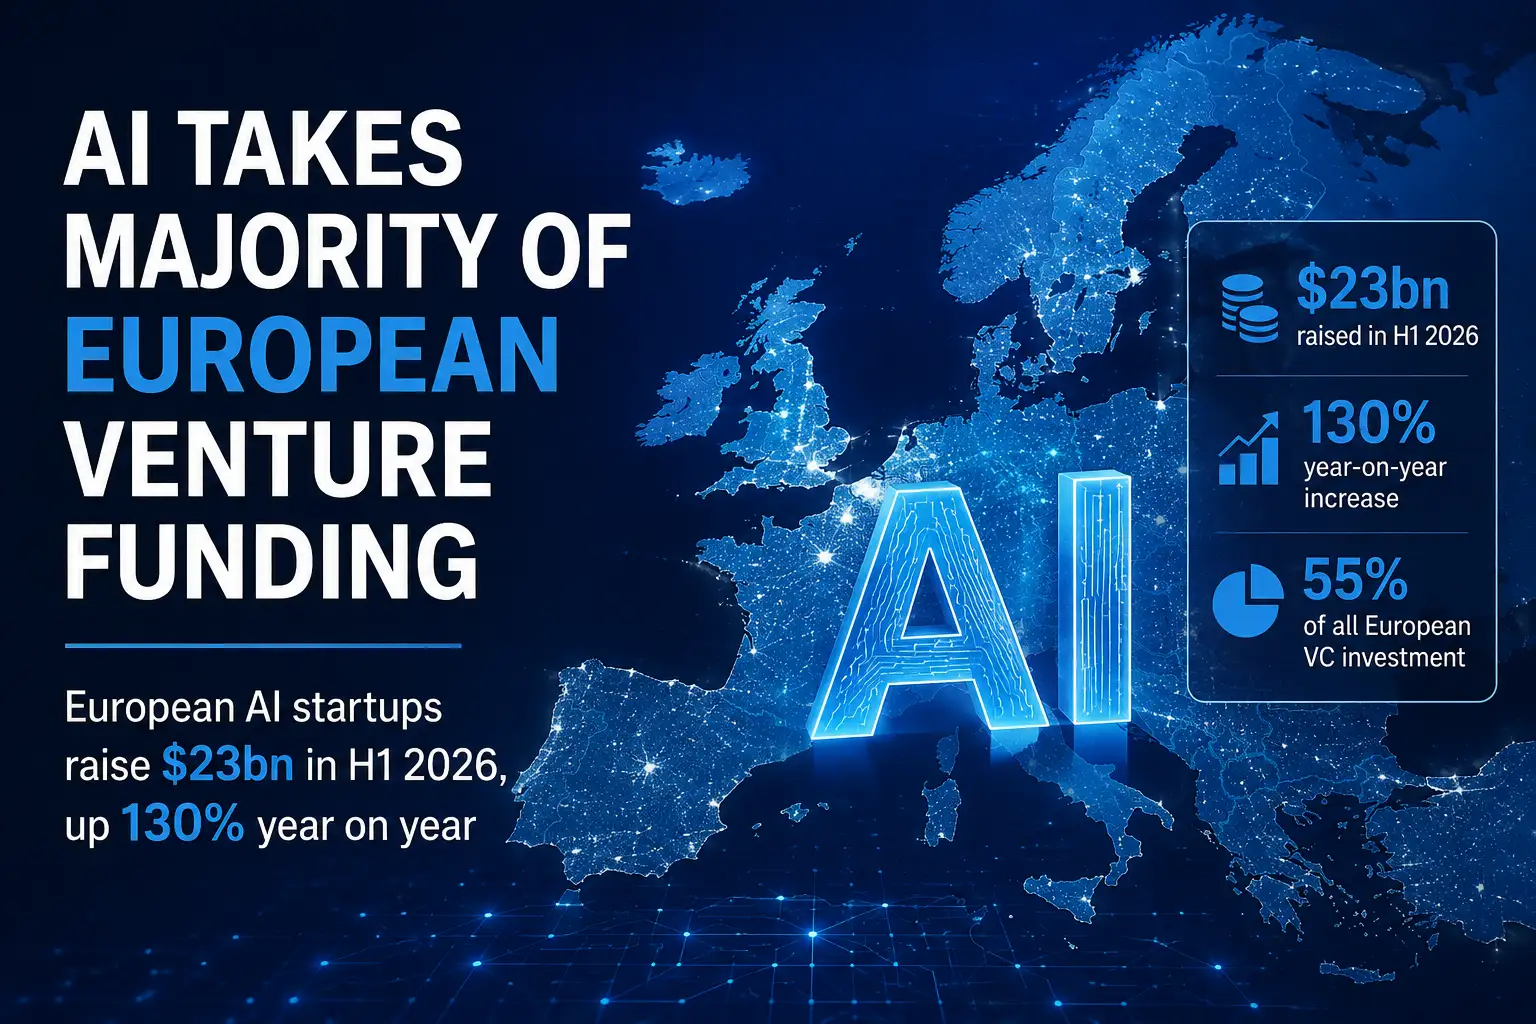
AI takes majority of European venture funding as money floods into few firms
-
RABAM raises $500,000 ahead of Series A round
Why financial literacy looks different when you live between two countries
BOSS Money
Corporate Contributor
- Published
- Banking & Finance
TOP STORIES
-
Why financial literacy looks different when you live between two countries
-
TalkTalk sells majority stake in Telecom Acquisitions as founder Nigel Barnett regains control
-
Company closures soar ahead of tax rises as new Budget looms
-
Credit beyond scoring: where to find fintech’s next big opportunity
-
UK economy grows faster than first thought as household incomes bounce back
-
British Chambers unite against 'Made in Europe' rules amid fears for UK industry
-
Kuwait deepens capital market reforms as Boursa Kuwait scoops triple honours
-
Michael Dell becomes world's fourth-richest person as Forbes reveals the ten wealthiest billionaires
-
MPs tell Government to reject Thames Water creditors as utility nears insolvency
-
The municipal pension fund setting a new standard in South Africa
-
BP appoints Ian Tyler chairman after Albert Manifold ousting
-
They came to Malta as nomads. Then stayed on as founders
-
Fuel management software is becoming a working-capital tool for smaller fleet businesses
-
Tokenisation, trust and the future of European property law
-
LEGO sales soar 22% amid World Cup, F1 and Star Wars push
-
Why entrepreneurs choose the wrong countries
-
Finance and Investment in Focus
-
Aventus Group wins three European Business Awards after loan growth tops 30 per cent
-
European investors can now trade thousands of US stocks through Kraken
-
Ex-Lenovo executive Sabine Hammer to lead Infinigate’s DACH business
-
NVIDIA teams up with Wall Street giants in $500bn push to fund AI boom
-
BAC and the future of regional corporate banking in Central America
-
How AI trading bots are reshaping retail currency trading in Europe
-
AI takes majority of European venture funding as money floods into few firms
-
RABAM raises $500,000 ahead of Series A round