
Technology has made payments and money management easier, but access to credit remains a more complex challenge. Solving it requires a combination of banking expertise, an entrepreneurial approach, and technological intelligence, writes Oleg Boiko
Opening an account in an app, transferring money, or buying securities has become much easier these days. Yet a convenient financial interface does not necessarily mean access to financing. A customer may use digital services every day and still receive no credit offers from their bank.
This, in my view, is where one of the most interesting opportunities for financial businesses lies: serving people whom traditional banks assess too cautiously and regard as insufficiently eligible. This is the group we have focused on at our company. But serving this market is far more difficult than launching another payments app.
It is useful to divide financial inclusion – the expansion of access to financial services – into two parts. The first covers mostly transactional services like payments, transfers, investment services, personal finance management, and so on. The second concerns lending. These areas have different economics and fundamentally different costs of getting things wrong.
In transaction services, technology can speed up an operation, lower its cost and improve the customer experience. Lending adds a central question: will the money be repaid? The answer becomes clear only later, as the loan portfolio is tested by customers’ payment behaviour and changing economic conditions.
This explains banks’ caution. Expanding access to credit for a broader audience means working with borrowers for whom less conventional data may be available. For an institution seeking low and predictable risk, doing so requires a strong technological and economic case.
Credit fintech startups face another barrier: raising capital. An investor must take on both the risk of a young technology company and the risk of its lending model. Scaling depends on portfolio quality: growing loan volumes fast can create value for the startup, but they can also increase future losses.
For this reason, our investment approach focuses on businesses in which we can play an active role and that complement our own operational, managerial and technological expertise. What matters to us is the opportunity to apply our capacity, not simply provide capital. This approach is closer to private equity funds’ approval, even when the company is at a relatively early stage.
Limited competition in credit fintech should not be misleading. It also reflects the difficulty of entering the market. Success requires a team that combines banking discipline, an entrepreneurial willingness to work with uncertainty and the ability to build its own technology. We have brought these capabilities together in our company. In credit fintech, they must work in tandem: technology must account for the economics of lending, while business growth must remain within the capacity to manage risk.
Our focus is so-called ‘near-prime’ consumer lending: serving borrowers who are close to the most creditworthy category but do not fully meet standard bank criteria. I believe this is one of the most interesting opportunities in the financial market. A bank’s rejection does not always mean a borrower cannot repay. It may reflect the limited ability of the bank to assess risk of such customers of its assessment model or the high cost of serving that particular customer.
Our commercial challenge is to process this demand more accurately and offer a product with viable economics for both sides. Financial inclusion works when a lender can distinguish an underestimated borrower from one for whom additional debt would become a problem. Simply approving more applications does not solve that challenge.
Large technology platforms (big tech) look like natural contenders in this market. They have customer bases, recognisable brands, convenient interfaces and data on user behaviour. For specialist lenders, including us, they are potentially formidable competitors. But those advantages do not replace the ability to manage credit risk, creative product development and focus on credit first.
Moving into financial services also changes the demands placed on the business itself. The regulatory framework and group structure can matter as much as the quality of the app. Platforms therefore face a strategic choice about which financial capabilities to develop themselves and which to obtain through partnerships.
For many technology platforms, operating under a banking licence and entering the associated regulatory regime does not make economic sense; in many cases, the law does not even permit it.
In my view, a hybrid model is the most viable for all large retail companies. A company builds its own products where it has sufficient expertise and can operate efficiently, while specialist partners provide other services. To the customer, this can look like a single ecosystem. For the business, it distributes responsibility without requiring it to recreate the entire financial industry in-house.
Artificial intelligence can make this model more efficient, but its impact also needs to be considered by application.
In customer service, document processing, internal operations, and the detection of suspicious activity, the effects of automation are easier to measure. AI agents can track how long a task takes, how much it costs, and how the number of errors changes. Lowering these costs directly supports financial access: the less it costs to serve a customer well, the more people a company can serve sustainably.
Credit decisions are more complicated. An algorithm’s answer is not enough. Regulators and financial institutions need ideally to understand the algorithm for the decision, how robust it is, and how to detect mistakes. The ability to audit the model and assign clear responsibility is essential.
In our work, the scope for using AI depends partly on the type of licence and the requirements of each market. Some areas offer more room to introduce new tools. But technological freedom does not remove the need to control outcomes.
The value of AI in lending will therefore depend on whether it can be integrated into a process that can be managed and supervised. Auditable decisions, data quality controls and human involvement where needed become part of the product itself. The pace of automation must match the ability to monitor its consequences.
Fraud prevention illustrates technology’s dual role. Analysing how someone behaves while completing an application can help identify unusual actions and flag cases for further review. But fraudsters adapt and use automation too. Maintaining an advantage requires models to be updated continuously: an algorithm deployed once will not provide lasting protection.
For small and medium-sized businesses, AI’s potential also extends well beyond lending. Automating bookkeeping, cash flow analysis, payment planning, and customer service can reduce administrative costs. Better information about a business’s financial position can, in turn, provide a stronger basis for assessing its financing needs.
The way people choose financial services will change as well. A user will be able to describe a specific goal – finance a purchase, spread out payments, or compare terms – and get help finding a suitable solution. In this model, financial companies will compete to be included in a well-founded recommendation. Transparent terms and a close fit between the product and the customer’s needs will become especially important.
A convenient recommendation, however, is not necessarily a reliable one. A system’s ability to compare offers quickly does not establish the quality of its decisions over time. In finance, trust is built on results that can be verified.
The next stage of development in credit fintech, in my view, will be defined by how far technology can expand the customer base of lenders while keeping risk and costs at acceptable levels. For our company, this is a practical challenge: understand borrowers better to create a convenient and useful ecosystem, serve them more efficiently, and preserve portfolio quality as the business grows.
The ability to meet all these conditions will determine who can turn financial inclusion into a sustainable business.
Oleg Boiko is an entrepreneur and investor with more than four decades of experience across financial services, technology and international investment. He is the founder and chairman of Finstar Financial Group, a private investment group with approximately US$2 billion in assets under management and investments across more than 20 countries. His work has focused particularly on fintech and technology-enabled financial services in developed and emerging markets.
Boiko’s investment philosophy emphasises long-term growth, operational discipline and the ability to identify and adapt to emerging economic and technological trends. Beyond business, he supports socially significant initiatives, including the development of the Paralympic movement.
Further information
Produced with support from Finstar Financial Group, a private investment group with approximately US$2 billion in assets under management and investments across more than 20 countries in Europe, Asia, Latin America and the CIS.
READ MORE: Why entrepreneurs choose the wrong countries. Global expansion is often presented as a projection of financial strategy. In reality, it is a test of institutional judgment and organisational maturity. International investor and fintech entrepreneur Oleg Boiko explores why understanding the rules behind a market – not just its economics – is the real foundation of long-term international success.
Do you have news to share or expertise to contribute? The European welcomes insights from business leaders and sector specialists. Get in touch with our editorial team to find out more.
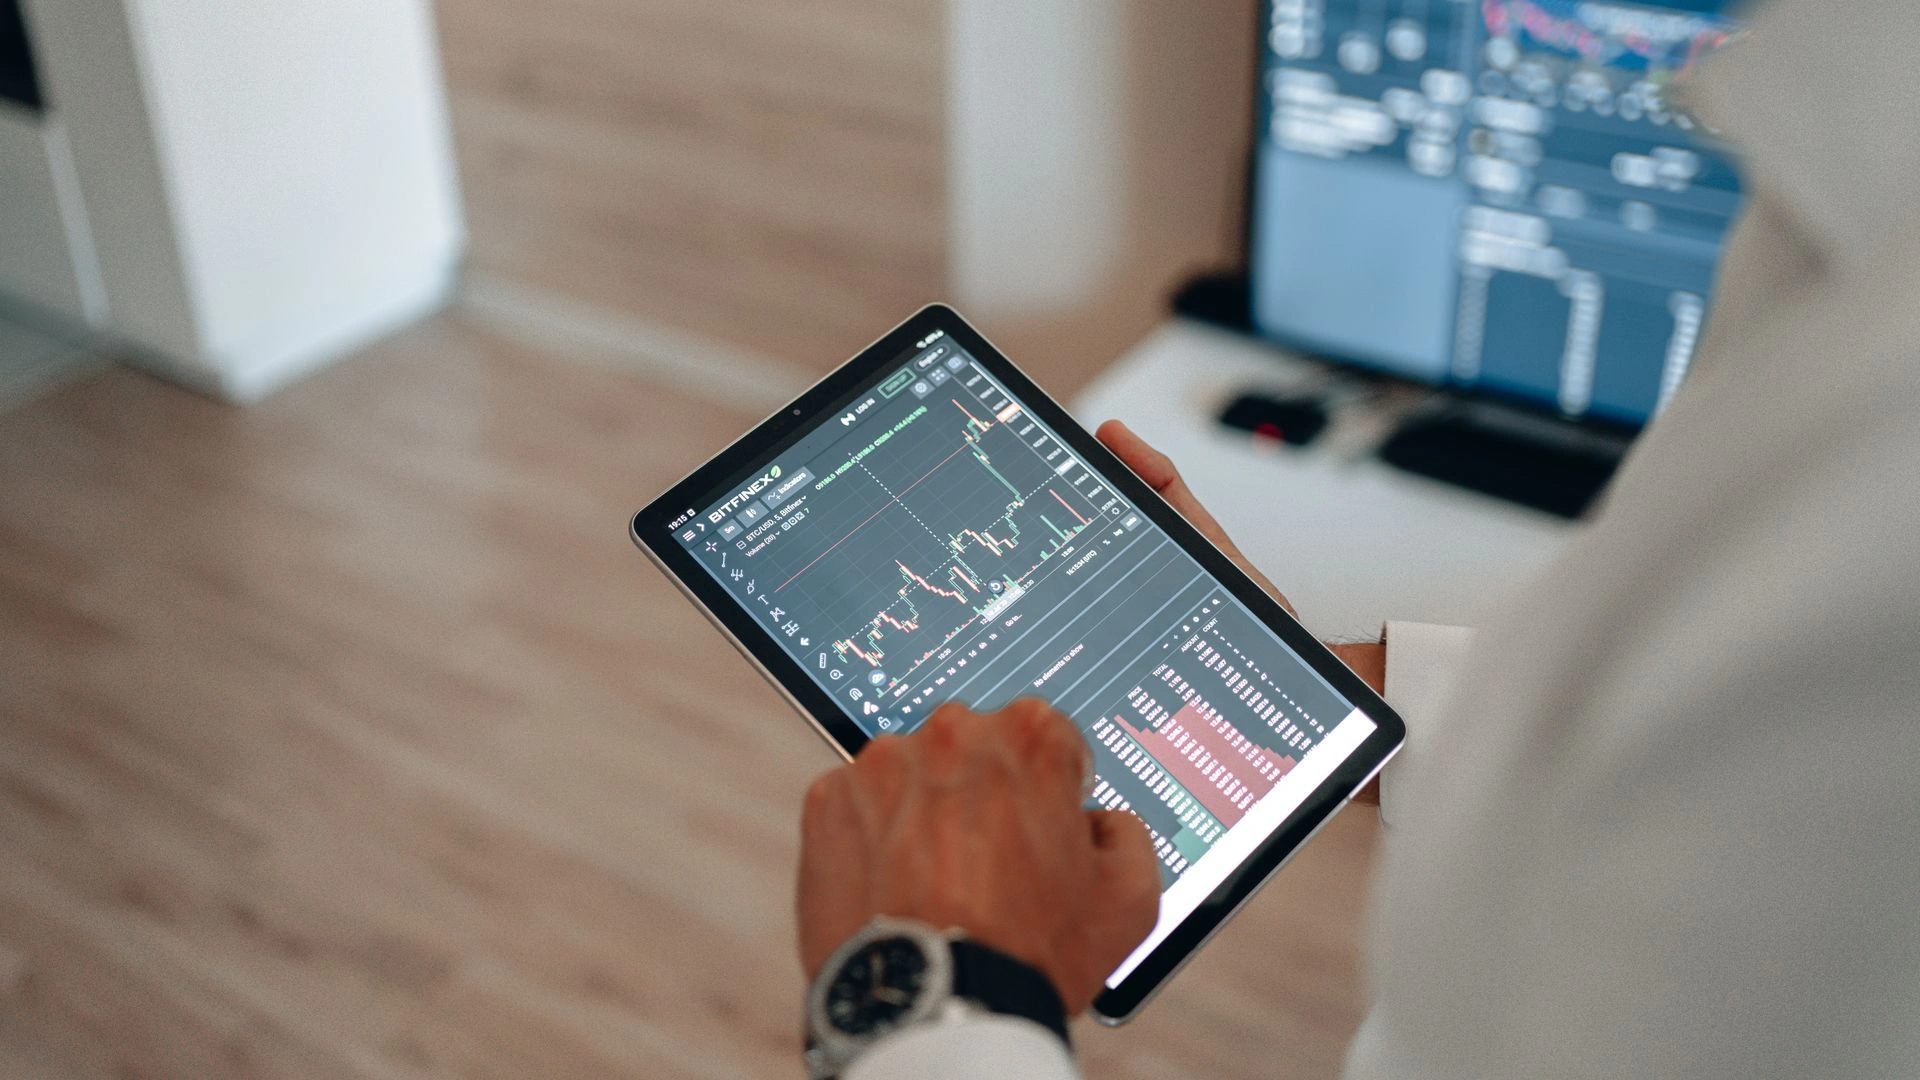
Main image: Digital lenders are using technology and alternative approaches to credit assessment to reach borrowers who may fall outside traditional banks’ lending criteria. Credit: Mikhail Nilov via Pexels